COMMENTARY:
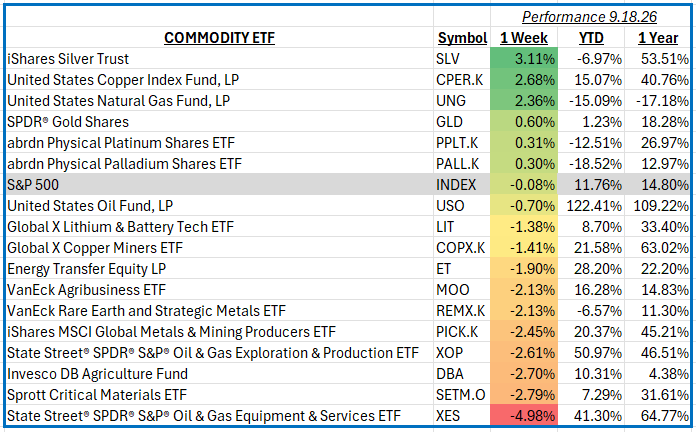
The S&P 500 returned -0.08% for the week, while global commodity markets continued to reflect a mix of geopolitical risk, inflation concerns and shifting expectations for economic growth. Oil remained near $100 per barrel as disruptions involving Saudi infrastructure and the Strait of Hormuz kept supply concerns elevated. At the same time, the Federal Reserve raised interest rates 25 basis points, adding pressure to commodities through higher yields and a stronger focus on inflation.
Precious Metals led the commodity complex, with silver rising 3.11%, supported by continued investor demand for hard assets amid geopolitical uncertainty and inflation concerns. Gold also remained firm, although higher interest rates created some headwinds for precious metals. Gold and silver both advanced after the Fed decision as Treasury yields and the dollar eased, highlighting the competing forces influencing precious-metals markets.
Industrial Metals also performed well, with copper gaining 2.68%. Copper-related mining companies including Freeport-McMoRan, Southern Copper and BHP benefited from strength in the underlying metal. Longer-term demand expectations remain tied to electrification, grid investment, data centers and artificial-intelligence infrastructure, while copper’s designation as a U.S. critical mineral continues to focus attention on supply security.
Natural Gas and Energy delivered mixed results. Natural gas gained 2.36%, helped by continued power-sector demand and relatively modest storage injections, while LNG feedgas demand also supported prices. U.S. natural gas futures gained 2.9% for the week. Meanwhile, oil prices remained volatile around $100 as Middle East supply disruptions were partially offset by expectations that some Saudi pipeline capacity could return.
Critical Materials and Oilfield Services were the weakest areas. Critical-materials investments declined 2.79%, while oil-and-gas equipment and services fell 4.98%. Oilfield-service companies including Baker Hughes, Halliburton and SLB faced pressure despite elevated crude prices, as investors weighed whether sustained geopolitical disruptions would translate into durable increases in drilling activity. The group also contended with renewed uncertainty surrounding future energy demand and capital spending.
Overall, commodity markets remained highly differentiated this week. Silver, copper and natural gas provided leadership, while oil-related equities and critical-materials exposures lagged. The combination of geopolitical supply risks, higher interest rates and continued demand from electrification and AI infrastructure should remain important drivers across the commodity landscape in the weeks ahead.