COMMENTARY:
The S&P 500 declined 0.47% for the week ending October 23, 2026, as investors weighed rising geopolitical tensions, accelerating energy prices, and renewed inflation concerns. Global commodity markets experienced divergent performance, with crude oil rallying on supply-disruption fears while natural gas and precious metals declined. Attacks affecting Middle Eastern energy infrastructure and shipping routes heightened concerns about oil availability, while higher energy prices reinforced expectations that interest rates could remain elevated. Investors also monitored economic indicators and anticipated the Federal Reserve’s upcoming policy decision.
Crude Oil and Energy Infrastructure
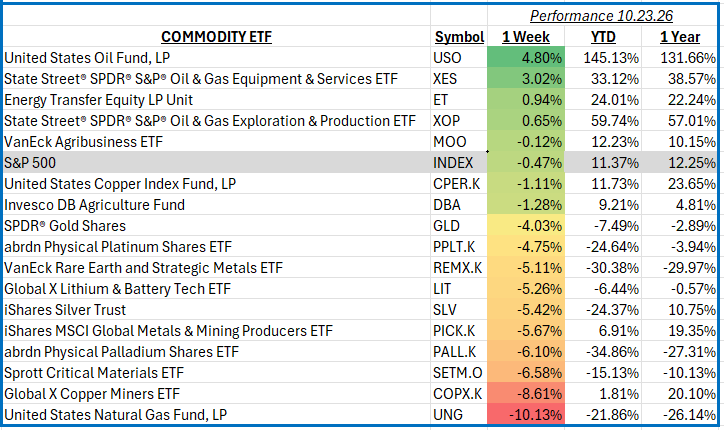
Crude oil investments led commodity-related performance as geopolitical tensions lifted prices above $100 per barrel for U.S. West Texas Intermediate crude. Oil advanced amid reports of Houthi attacks on Saudi Arabian infrastructure and continued shipping risks around the Strait of Hormuz. Oil futures gained approximately 4.3% for the week, while the United States Oil Fund advanced 4.80%, outperforming the S&P 500 by 5.27 percentage points. Integrated producers such as Exxon Mobil and Chevron benefited from stronger crude prices, while oilfield service providers including Schlumberger and Halliburton attracted attention as elevated prices supported exploration and production spending. Energy infrastructure partnerships, including Energy Transfer, also remained relevant as investors assessed transportation capacity and demand for energy-related infrastructure.
Precious Metals and Mining
Precious metals weakened as rising energy prices intensified inflation concerns and increased expectations for tighter monetary policy. Gold declined approximately 4% for the week, falling below $4,000 per ounce, while silver dropped about 5.7%. Higher interest-rate expectations reduced the appeal of non-income-producing precious metals. Gold miners such as Newmont and Agnico Eagle Mines faced pressure, while silver producers including Pan American Silver were exposed to the broader metals downturn. Platinum and palladium investments also remained vulnerable to changing industrial demand and investor sentiment.
Industrial Metals and Critical Materials
Copper mining declined 8.61%, underperforming the S&P 500 by 8.14 percentage points. Copper prices weakened amid concerns about industrial demand and broader metals-market selling. Producers such as Freeport-McMoRan, Southern Copper, and Antofagasta faced pressure as investors reassessed the outlook for manufacturing, infrastructure investment, and global economic growth. Lithium and rare-earth companies also remained sensitive to electric-vehicle demand, battery investment, and the longer-term transition toward electrification.
Natural Gas and Agricultural Commodities
Natural gas was the weakest exposure, falling 10.13% as milder weather expectations reduced near-term heating demand. The decline reflected a sharp reversal from stronger energy-market performance elsewhere. Agricultural commodities also experienced mixed conditions, with wheat and corn prices under pressure amid changing supply expectations and demand conditions. Fertilizer producers and agricultural-equipment manufacturers remained sensitive to crop prices, input costs, and global planting economics.
Closing Thoughts: Commodity markets finished the week sharply divided, with geopolitical risks supporting crude oil while natural gas, precious metals, and industrial mining investments struggled. Energy supply developments, inflation expectations, and the Federal Reserve’s next policy decision remain important factors for global commodity investors.