COMMENTARY:
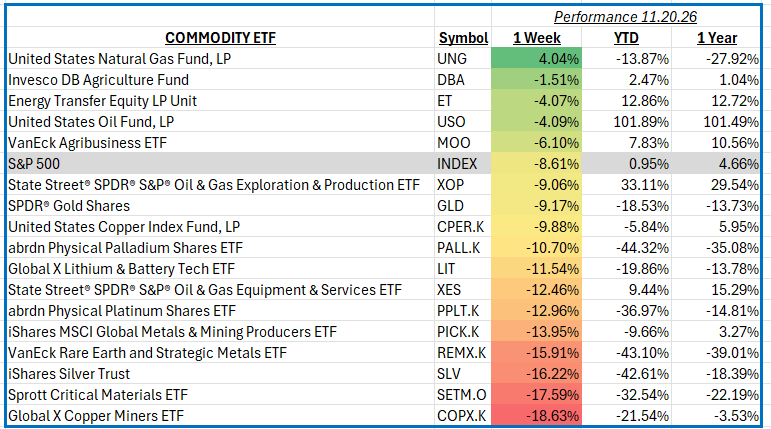
For the week ending November 20, 2026, the S&P 500 returned -8.61%. Commodity markets offered little shelter from the selloff: gold, silver, copper and crude oil fell as a stronger U.S. dollar, expectations of higher interest rates and a pullback from risk weighed on prices. Natural gas bucked the trend, supported by a smaller-than-expected storage increase and forecasts for colder weather. Meanwhile, improving Middle East oil flows raised concerns about a potential supply surplus.
Energy production and transport: Natural gas exposure led the listed commodity themes, gaining 4.04% and outperforming the S&P 500 by 12.65 percentage points. The smaller 20-billion-cubic-foot storage build, below market expectations, supported gas prices, although mild near-term weather tempered demand prospects. Energy Transfer declined 4.07%; its pipeline and storage business is tied to energy flows, while oilfield-service companies such as SLB and Baker Hughes represent the drilling and production supply chain. Crude oil fell for a third consecutive week as stronger Middle East exports outweighed geopolitical concerns.
Precious metals: Gold and silver weakened despite their traditional safe-haven appeal. Higher rate expectations and a firmer dollar pressured metal prices; silver fell more sharply than gold during the week. Newmont and Barrick are major gold producers, while Wheaton Precious Metals has exposure to both gold and silver. Platinum and palladium also declined, weighing on related metal exposures.
Industrial and critical materials: Copper and mining shares came under particular pressure as investors reassessed growth-sensitive commodities and businesses linked to electrification. Critical-material exposures fell 17.59%, while copper-mining shares lost 18.63%, making them the weakest listed exposure and 10.02 percentage points below the S&P 500. Freeport-McMoRan was among the notable copper producers affected. Lithium, rare-earth and diversified mining companies faced the same difficult backdrop.
Agriculture: Agricultural commodities were comparatively resilient: the agriculture exposure declined 1.51%. Soybeans and wheat received some support from export demand, while corn prices were weaker. Deere and Corteva represent agricultural equipment and crop-input businesses within the broader farm supply chain, though the commodity exposure itself tracks agricultural futures.
Across the value chain: Oil services, energy transport, precious-metal producers, battery-material miners and agricultural suppliers all responded to distinct supply and demand forces. Several products in these categories hold futures or physical metals directly, so their returns do not depend on individual company stocks.
Overall, natural gas was a bright spot, while metals and oil-linked markets struggled. It was a volatile week for commodities and their related industries.